
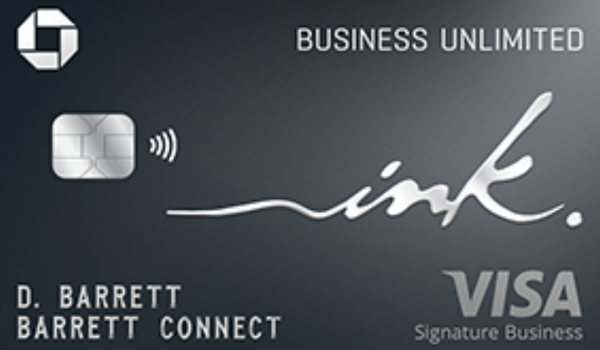
Chase Ink Business
Business rewards Employee cardsApplying for Chase Ink Business Credit Cards can feel like a smart move when your business expenses are growing and you want those costs to generate value. For U.S. business owners, the appeal is clear: these cards can separate personal and company spending while turning purchases into cash back, points, or travel value.
However, the right choice depends on your business model. A freelancer may need simple rewards, while an agency may spend more on advertising. Meanwhile, a local shop may care about office supplies, phone bills, and employee cards. So, before applying, compare the Ink options with your real monthly spending.
Main benefits of the credit card
The biggest benefit is variety. Chase Ink Business Credit Cards include options for different spending patterns, which helps owners avoid choosing a card that looks attractive but does not match their expenses.
Ink Business Preferred can work well for businesses that spend on travel, shipping, online advertising, internet, cable, and phone services. It also connects with Chase Ultimate Rewards, which may add more travel value for owners who redeem strategically.
Ink Business Cash can be useful for office-focused spending and selected business categories. In addition, it has no annual fee, which makes it attractive for smaller businesses watching fixed costs.
Ink Business Unlimited is easier to manage because it offers flat cash back on business purchases. Therefore, it may fit owners who do not want to track categories every month.
These cards can help with:
- Separating business and personal expenses
- Earning rewards from routine company purchases
- Adding employee cards with spending controls
- Building a clearer expense trail
- Supporting cash flow during short billing cycles
Still, rewards should not justify overspending. If the business cannot pay the balance, APR can erase the value quickly.
Possible drawbacks before applying
The main drawback is interest. Some Ink cards offer introductory APR periods, but regular variable APRs can become expensive after the promotional window ends. Because of that, these cards work best for owners who pay in full or plan short-term purchases carefully.
Another limitation is category fit. Ink Business Preferred can be strong for certain business expenses, but it may not be the best choice for every owner. If your company mostly buys inventory, pays contractors, or handles rent, another card may fit better.
The annual fee also matters. Ink Business Preferred has a fee, while Ink Business Cash and Ink Business Unlimited do not. Therefore, the Preferred version needs enough rewards or travel value to justify its cost.
Finally, Chase approval can be selective. Strong personal credit, manageable debt, real business activity, and clean application history can all influence the decision.
Requirements and documentation for approval
Applicants should expect Chase to review both personal and business details. Even when applying for a business card, small business owners often rely on personal credit during the approval process.
You may need to provide:
- Full legal name and U.S. address
- Social Security number
- Business name or legal name
- Business tax ID, when available
- Business structure
- Industry type
- Annual business revenue
- Estimated monthly card spending
- Personal annual income
Sole proprietors, freelancers, consultants, online sellers, and 1099 workers may apply when they have real business activity. However, the business should not be invented only to access a card.
Approval usually favors applicants with good credit, stable income, and low utilization. If recent late payments, collections, or multiple applications appear on the file, approval odds may drop.
Chase Ink Business Credit Cards
What really works
Chase Ink Business Credit Cards are competitive because the lineup includes both no-annual-fee and annual-fee options. Ink Business Cash and Ink Business Unlimited can be easier for smaller businesses because they avoid fixed card costs.
Ink Business Preferred has an annual fee, but it may justify the cost for businesses that use bonus categories and Chase Ultimate Rewards. Compared with American Express Blue Business Cash or Capital One Spark Cash, the best choice depends on spending style.
Chase Ink Business Credit Cards can be strong when business spending matches the right card. Ink Business Cash rewards selected business categories, while Ink Business Unlimited keeps things simple with flat cash back.
Ink Business Preferred can stand out for travel and selected business expenses. However, if the owner wants one predictable rate everywhere, Capital One Spark Cash or American Express Blue Business Cash may feel simpler.
APR is not the strongest reason to choose Chase Ink Business Credit Cards. The regular variable APR can become expensive after any introductory period ends.
Ink Business Cash and Ink Business Unlimited may help with short-term planning because they can offer 0% intro APR on purchases. However, owners should pay down balances before the regular APR begins.
Chase Ink Business Credit Cards often compete strongly on welcome offers. Ink Business Preferred can appeal to businesses with larger planned expenses, while Ink Business Cash and Ink Business Unlimited may suit owners with moderate spending targets.
Still, a welcome offer should never force unnecessary purchases. If your company cannot meet the requirement through normal expenses, the bonus may create more pressure than value.
The overall value depends on business behavior. Chase Ink Business Credit Cards can work well for owners who track expenses, pay on time, and choose the card that fits their categories.
They may not be ideal for owners seeking long-term financing. In that case, a business line of credit, equipment loan, or SBA microloan may offer more structured repayment.
This accordion shows that Chase Ink Business Credit Cards can be powerful, but only when matched to the right business profile. The strongest value comes from using normal expenses strategically, not increasing spending to chase rewards.
Why Chase Ink Business Credit Cards can reward organized owners
Chase Ink Business Credit Cards can be a strong choice for owners who want rewards, cleaner expense tracking, and flexible options for different business needs. The lineup works best when the selected card matches real spending categories.
However, business owners should compare APR, annual fee, welcome offer requirements, cash flow, and payment habits before applying. The best card is not always the one with the biggest bonus. It is the one that supports your company without creating expensive debt.
Want to know how to get approved faster? See the next page.
SEE HOW TO APPLY
By clicking, you will remain on this website

 How to apply for the Surge® Mastercard® and rebuild credit without ignoring the fees <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'>See how Surge Mastercard works, including approval requirements, APR, fees, credit reporting, drawbacks and lower-cost card alternatives.</p>
 How to get the Serve® Pay As You Go Visa® and control spending without a credit check <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'>See how Serve Pay As You Go Visa works, including no credit check access, prepaid benefits, fees, drawbacks and smart alternatives.</p>