
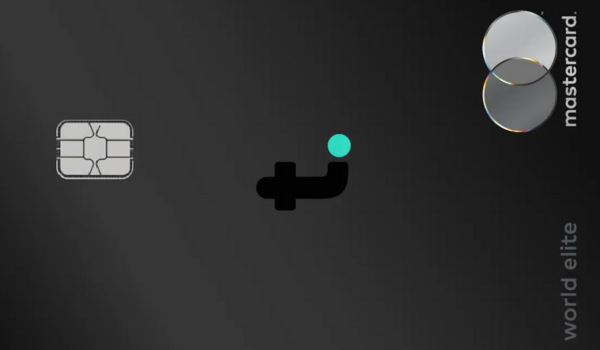
TOMO Mastercard
NO ANNUAL FEE FAST APPROVALA modern way to access credit without relying on a traditional score
Getting approved for a credit card can feel overwhelming, especially if you are rebuilding your financial life or applying for your very first product. The Card TOMO Mastercard brings a different kind of opportunity, especially for applicants who cannot qualify for traditional cards due to low credit scores or limited history. Unlike many mainstream products, this card evaluates your income flow, bank activity and financial habits instead of relying on a minimum required credit score. For many U.S. consumers, this creates a more human, less restrictive path to financial access.
The emotional appeal behind the Card TOMO Mastercard is simple. It represents a fresh start. Many applicants describe the feeling of finally being seen not for their past credit mistakes but for their current income and responsible banking behavior. This shift alone has helped freelancers, 1099 workers, gig-economy earners and first-generation immigrants find their place in the credit market.
Benefits of the TOMO Mastercard
Before listing the main benefits, here is a quick note: these advantages matter because they remove many of the barriers traditional cards create.
• no APR charges due to the weekly payment schedule, allowing consumers to avoid interest entirely
• zero annual fee, something uncommon among cards designed for credit building
• fast approval processing, often within minutes when bank verification succeeds
• reporting to all major credit bureaus, helping applicants grow their file consistently
After reviewing these benefits, it becomes clear why this card appeals to consumers who prioritize transparency and predictability.
Another highlight is the spending limit, which is based on your cash flow rather than a reported score. Some users receive limits higher than expected because the underwriting system prioritizes real-time financial behavior instead of outdated score metrics from months earlier.
Drawbacks and limitations to consider
Before listing the weaknesses, a short reminder: every card has trade-offs, and knowing them prevents frustration later.
• no traditional revolving balance, meaning you cannot carry debt month to month
• weekly payments may feel restrictive for consumers accustomed to longer billing cycles
• bank connection is mandatory and can lead to declines if the system cannot verify data
• predictable credit limits may appear lower for applicants with irregular deposit frequency
After reviewing these drawbacks, most applicants still find the card useful, but it is important to understand how these limitations fit your financial routine.
Some consumers also report that the card may not be ideal for large emergency purchases because you cannot stretch payments across months. This is a common limitation among credit-building products.
Requirements and documentation to qualify
TOMO uses alternative underwriting. Applicants do not need a specific FICO score, but they must meet U.S. compliance and financial stability criteria. You must be at least eighteen years old with a valid SSN or ITIN. Access to an active checking account is mandatory because underwriting decisions depend on your transaction history.
The system analyzes your recurring deposits, account age, average balance and frequency of negative transactions. Freelancers and independent contractors can qualify as long as deposits are consistent. Income proof is not uploaded as documents but verified directly through your banking data, which makes the process faster for most applicants.
TOMO Mastercard vs. Alternatives
Below is a comparative overview designed for users evaluating multiple options.
Comparison Table: TOMO Mastercard vs Competitors
| Feature / Card | Card TOMO Mastercard | Capital One Platinum Secured | Discover it Secured |
| Minimum required credit score | None | Typically 580 or higher | Typically 600 or higher |
| Annual fee | 0 USD | 0 USD | 0 USD |
| APR | No APR due to weekly auto-pay | 29.99 percent variable | Around 27.99 percent variable |
| Deposit required | No | Yes, starting at 49 to 200 USD | Yes, starting at 200 USD |
| Best for | New borrowers, freelancers, thin files | Rebuilding credit | Earning cash-back while rebuilding |
This table shows a crucial difference. TOMO offers a no-deposit model, while the competitors rely heavily on secured structures. The lack of APR also helps consumers avoid long-term debt.
Conclusion: is the TOMO Mastercard right for you
The Card TOMO Mastercard is a strong option for applicants seeking a fresh start, predictable payments and a credit-building pathway not tied to traditional score requirements. It can be especially helpful for people with thin credit files, irregular income patterns or self-employment backgrounds. Compare your cash flow, simulate approval odds and select the card that best aligns with your long-term financial strategy.
By clicking, you will remain on this website.

 DESTINY MASTERCARD: your second-chance credit option built for real financial recovery <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'>Discover how the DESTINY MASTERCARD works, its benefits, approval rules and how it compares to rebuilding cards.</p>
 CAPITAL ONE VENTURE REWARDS: your fast-track card for premium travel benefits <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'>Discover how the CAPITAL ONE VENTURE REWARDS card works, its benefits, approval rules and how it compares to top travel cards.</p>
 BJ’S ONE PLUS MASTERCARD: a smarter way to boost rewards and everyday savings <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'>Explore BJ’S ONE PLUS MASTERCARD benefits, drawbacks, approval rules and comparisons to choose the best card for your financial profile.</p>