
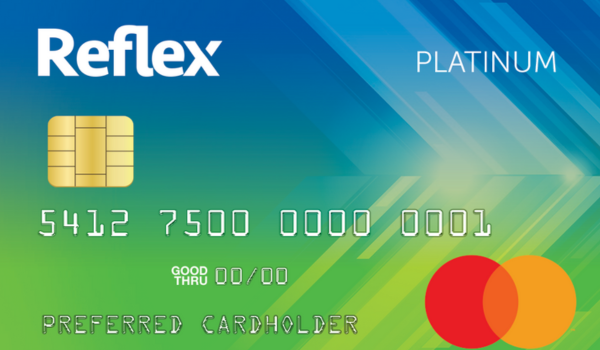
REFLEX CARD MASTERCARD
NO DEPOSIT REQUIRED FAST APPROVALUnderstand the benefits, drawbacks and approval rules before choosing this rebuilding card
Getting approved for a credit card is often more emotional than people admit. For someone rebuilding their financial life, receiving that approval email feels like a turning point. The REFLEX CARD MASTERCARD gives many Americans that moment of relief. It offers a real unsecured credit line for people who have struggled with rejections, limited options and low credit ceilings. Because the card is geared toward subprime borrowers, the approval process feels far more welcoming than what traditional banks provide.
The psychological impact matters because credit rebuilding is not just technical, it is personal. Consumers who get approved usually describe the feeling as “finally getting a second chance.” Understanding how the card works helps you decide whether it truly supports your financial goals or whether the fees outweigh the benefits.
Benefits of the REFLEX CARD MASTERCARD
A quick intro prepares the reader for positive aspects of the card.
Below are the strengths that attract credit rebuilders.
After the list, a sentence reinforces clarity.
Some notable benefits include:
• Unsecured credit line with no upfront deposit
• Monthly reporting to all three major credit bureaus
• Mastercard acceptance nationwide for online and in-store purchases
• Potential credit line increases after several months of positive use
• Fast application process with near-instant decisions
• Approval available for W-2 employees, freelancers and 1099 contractors
These features explain why the card is popular among consumers recovering from financial setbacks.
Drawbacks You Should Consider Before Applying
A short intro keeps the analysis balanced.
Despite its advantages, the card includes several limitations and costs.
After setting the stage, the limitations become easier to understand.
Common drawbacks include:
• High variable APR that can increase monthly debt quickly
• Annual and monthly maintenance fees that reduce your effective credit limit
• No cashback program or rewards structure
• Lower starting limits compared to mainstream unsecured cards
• No introductory APR options or fixed monthly payment plans
• Significant fees for late or returned payments
These downsides highlight why responsible usage is essential.
Requirements and Documentation Needed for Approval
A brief transitional sentence guides the reader into underwriting criteria.
The issuer evaluates credit history, income stability and identity verification before granting approval.
After this intro, the requirements appear clearly.
Typical requirements include:
• A minimum required credit score usually between 540 and 620
• Verifiable income using pay stubs, W-2s, tax returns or 1099 filings
• A valid Social Security number and U.S. address
• An active checking account with positive activity
• No recent major delinquencies or active bankruptcies
• Limited recent hard inquiries
These requirements help the lender estimate your repayment reliability.
A short reminder reinforces the nuance.
Some applicants with scores near 420 have been approved after improving their utilization and showing stable deposits.
Comparison: REFLEX CARD MASTERCARD vs Two Common Alternatives
A brief introduction helps contextualize the comparison.
To understand whether the Reflex Card is the right fit, it helps to compare it with two similar rebuilding products used by U.S. consumers.
| Feature | REFLEX CARD MASTERCARD | First Digital Mastercard | Capital One Secured |
| Type | Unsecured | Unsecured | Secured |
| Deposit Required | No | No | Yes |
| Rewards | No | No | No |
| Typical APR | High variable | High variable | Moderate |
| Ideal For | Low credit scores | Low credit scores | Beginners with savings |
A short sentence after the table helps finalize the comparison.
The table shows that Reflex is best for borrowers who want an unsecured option without deposits, while secured cards offer lower fees but require upfront savings.
Conclusion: Deciding Whether the REFLEX CARD MASTERCARD Fits Your Needs
The REFLEX CARD MASTERCARD can be an effective tool for rebuilding credit, but it demands disciplined usage. Its APR and fees require planning, and it makes sense only if you need an unsecured option and cannot qualify elsewhere. Before applying, compare fees, simulate different APR scenarios and choose a product aligned with your monthly budget. Compare, simulate and choose the best option based on your profile.
Want to get approved faster? Check the next page
By clicking, you will remain on this website.

 DESTINY MASTERCARD: your second-chance credit option built for real financial recovery <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'>Discover how the DESTINY MASTERCARD works, its benefits, approval rules and how it compares to rebuilding cards.</p>
 CAPITAL ONE VENTURE REWARDS: your fast-track card for premium travel benefits <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'>Discover how the CAPITAL ONE VENTURE REWARDS card works, its benefits, approval rules and how it compares to top travel cards.</p>
 BJ’S ONE PLUS MASTERCARD: a smarter way to boost rewards and everyday savings <p class='sec-title' style='line-height: normal; font-weight: normal;font-size: 16px !important; text-align: left;margin-top: 8px;margin-bottom: 0px !important;'>Explore BJ’S ONE PLUS MASTERCARD benefits, drawbacks, approval rules and comparisons to choose the best card for your financial profile.</p>